
Listed on 
 Years active
 English (Arabic)
 Chinese Simplified - 中文 (简体)
 Chinese Traditional - 中文 (繁體)
 English
 Japanese - 日本語
 Korean - 한국어 (대한민국)
 Portuguese - Português
 Russian - Русский
 Spanish - Español
 Thai - ไทย

 English (India)

Don't have an account?
Register via AppHave an account?
Login 15/09/2026 - 07:38 UTC
The US Dollar Index (USDX) continues to build momentum, strengthening to around 99.60 during Tuesday's Asian session. The Greenback is drawing solid support from heightened expectations of a Federal Reserve rate hike following hotter-than-expected US inflation data and surging energy prices. Financial markets have now priced in over a 90% probability of a rate increase at this week's Fed meeting, up sharply from around 60% a week ago. Traders are closely monitoring the upcoming FOMC statement and Fed Chair Kevin Warsh's press conference for signals regarding future monetary policy, while persistent Middle East tensions add further safe-haven demand for the US Dollar.
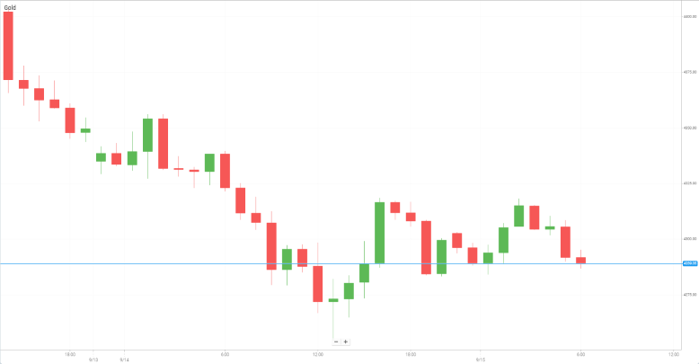
Gold struggles to register any meaningful recovery, remaining pinned near a multi-week low just below the $4,300 mark. The precious metal is hemmed in by a firm US dollar and rising bond yields, with the benchmark 10-year US Treasury yield crossing above 5%. Higher yields increase the opportunity cost of holding non-yielding bullion, capping upside potential despite underlying support from escalating Middle East geopolitical risks.
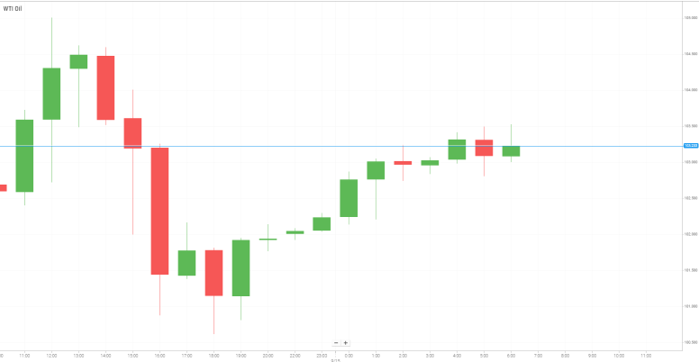
WTI Crude Oil extended its positive momentum into a second straight day, trading above $99.00 per barrel as supply disruption fears intensify. Geopolitical risk premiums remain elevated after Iran-backed Houthi forces launched a large-scale missile and drone attack against a Saudi air base in Khamis Mushait. Additionally, Iranian officials rejected the prospect of immediate diplomatic negotiations with the US, reinforcing concerns over persistent regional supply constraints.
Asian stock markets steadied on Tuesday following Monday's tech-led selloff, aided by a modest rebound in select technology shares. Market sentiment remains cautious as investors reassess corporate AI spending following calls from industry leaders—including Anthropic CEO Dario Amodei, OpenAI CEO Sam Altman, and Elon Musk—for stricter safeguards and a slower pace of next-generation model development. Broader Asian indexes traded mixed, while mainland Chinese equities held firm despite uneven domestic economic data. In individual equity movements during the latest trading session, Asian tech suppliers saw mixed results: SK Hynix fell 0.23%, Samsung Electronics dropped 0.81%, Alibaba slipped 0.07%, Tencent rose 1.94%, Baidu gained 0.55%, and JD.com advanced 0.70%.
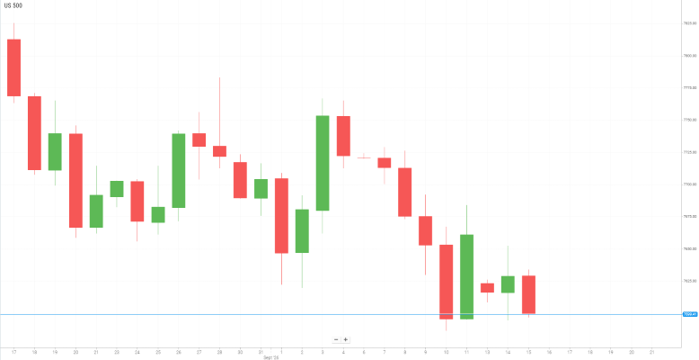
US equity futures signaled cautious trading as Wall Street digested high government bond yields and reassessed valuation metrics across the technology sector. The sector faced pressure from hardware and semiconductor names, with Nvidia dropping 3.32% and ASML sliding 6.19%. Conversely, cybersecurity names posted strong gains during the session, with CrowdStrike surging 13.83% and Palo Alto Networks gaining 13.13%.
Looking ahead to the rest of the week, financial markets face an event-packed economic calendar dominated by major central bank rate announcements. On Wednesday, the UK releases its latest annual CPI report, followed directly by the US Federal Reserve's interest rate decision, Monetary Policy Statement, Summary of Economic Projections, and FOMC press conference. Central bank action continues Thursday with the Bank of England's official rate decision, while the week concludes with the Bank of Japan's policy decision and press conference.
EUR/USD extends its decline for a fourth straight session, trading below 1.1550 during the Asian session on Tuesday and close to a one-month low reached the previous day. The pair remains under pressure as the US Dollar maintains a firm bullish bias ahead of the Federal Reserve’s two-day policy meeting, which begins today.
Expectations for tighter Fed policy, elevated US Treasury yields and renewed inflation concerns linked to higher energy prices continue to support the Greenback. The US 10-year Treasury yield is approaching the key 5% threshold, with rising inflation expectations adding to upward pressure on borrowing costs. Higher yields are boosting the appeal of the US Dollar, while ongoing tensions in the Middle East are providing additional support through safe-haven demand.
Geopolitical risks remain elevated, with Iran-backed Houthi forces claiming a missile and drone attack on a Saudi air base, while Iranian officials have ruled out an immediate return to negotiations with Washington. Continued tensions around the Strait of Hormuz are keeping oil prices elevated and adding to concerns over renewed inflationary pressure.
Despite the bearish backdrop, traders may remain cautious about placing fresh USD bets ahead of Wednesday’s FOMC decision. At the same time, the European Central Bank’s hawkish outlook may provide some support for the Euro and help limit the pair’s downside.
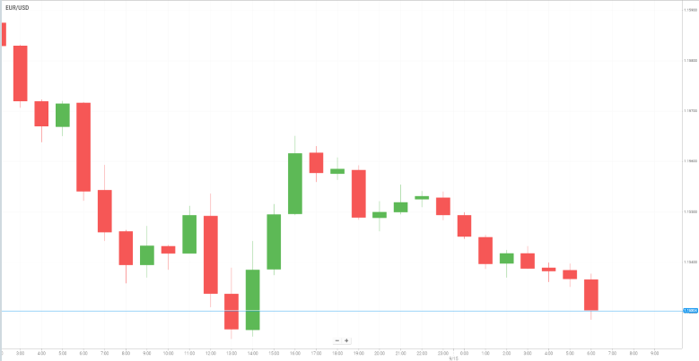
Gold struggles to stage a meaningful recovery on Tuesday, remaining close to a one-month low touched the previous day and trading below the $4,300 level. Investors are largely staying on the sidelines ahead of the Federal Reserve’s two-day policy meeting, with the focus firmly on Wednesday’s decision and guidance on the future path of interest rates.
Recent US inflation data has strengthened expectations for a near-term Fed rate hike, supporting the US Dollar and keeping pressure on the non-yielding precious metal. Attention will now turn to the Fed’s updated economic projections and dot plot, as well as Chair Kevin Warsh’s comments at the post-meeting press conference. Any indication of a more hawkish policy outlook could provide further support to the Greenback and weigh on Gold.
Meanwhile, rising energy prices are adding to inflation concerns and reinforcing expectations for tighter monetary policy. The global bond selloff has also pushed the US 10-year Treasury yield above 5% for the first time since 2023, further enhancing the appeal of the Dollar over non-yielding assets such as Gold.
Geopolitical uncertainty is providing some support to Gold’s safe-haven appeal, but the stronger US Dollar is currently limiting its upside.
Oil prices climbed on Tuesday as concerns over supply disruptions intensified following attacks on Saudi Arabian energy infrastructure that left the kingdom’s East-West pipeline offline.
The latest attacks by Iran-backed Houthi forces on Saudi Arabia have increased fears that the Middle East conflict could widen and further disrupt global energy supplies. Gulf Arab states also postponed planned discussions with Iran, adding to uncertainty over efforts to reduce tensions and ease shipping risks in the region.
The outage of Saudi Arabia’s East-West pipeline is particularly significant as the route allows the world’s largest oil exporter to bypass the Strait of Hormuz. The pipeline normally carries around 4 million barrels per day to the Red Sea port of Yanbu, equivalent to roughly 4% of global oil supply. A prolonged disruption could therefore tighten global markets considerably if Saudi Arabia is unable to restore exports.
Meanwhile, traffic through the Strait of Hormuz has also declined, with fewer than 10 commodity vessel transits recorded per day over the weekend compared with a recent 10-day average of 14. The waterway normally handles around one-fifth of global oil supplies, making any prolonged disruption a major risk for energy markets.
For now, traders remain highly sensitive to developments around both the East-West pipeline and Hormuz flows. Any signs of prolonged outages could push crude prices higher, while evidence of restored operations or progress toward de-escalation could ease some of the supply-risk premium.
Wall Street traded between gains and losses on Monday after a volatile session, with investors navigating renewed concerns over artificial intelligence, elevated oil prices and expectations for a Federal Reserve rate hike on Wednesday.
Technology stocks bore the brunt of the selling after Anthropic CEO Dario Amodei called for a slowdown in the development of advanced AI systems, raising fresh concerns about the sector’s lofty valuations. The pressure on markets was partly offset by a pullback in oil prices after President Donald Trump indicated that the US was open to the possibility of a deal with Iran.
Meanwhile, expectations for tighter monetary policy continued to weigh on sentiment. Markets are pricing in a 92.5% probability of a 25-basis-point Fed rate hike on Wednesday, following stronger-than-expected US inflation data and a robust August jobs report.
The ongoing selloff in US Treasuries has also pushed the 10-year yield to around 5%, its highest level since October 2023, reinforcing concerns over borrowing costs and financial conditions.
The materials contained on this document should not in any way be construed, either explicitly or implicitly, directly or indirectly, as investment advice, recommendation or suggestion of an investment strategy with respect to a financial instrument, in any manner whatsoever. Any indication of past performance or simulated past performance included in this document is not a reliable indicator of future results. For the full disclaimer click here.
Join iFOREX to get an education package and start taking advantage of market opportunities.
 A beginner's e-book
 $5,000 practice demo account
 A 12-part video course
 Trusted partner

 Featured partner
 By


