
Listed on 
 Years active
 English (Arabic)
 Chinese Simplified - 中文 (简体)
 Chinese Traditional - 中文 (繁體)
 English
 Japanese - 日本語
 Korean - 한국어 (대한민국)
 Portuguese - Português
 Russian - Русский
 Spanish - Español
 Thai - ไทย

 English (India)

Don't have an account?
Register via AppHave an account?
Login 16/09/2026 - 07:15 UTC
The US Dollar Index (USDX) strengthened around 0.14% in the latest session, trading near 99.70 as markets await today's Federal Reserve interest-rate decision. The Dollar remains supported by expectations of a 25-basis-point rate hike, with markets pricing a probability above 90%. Attention will shift to the Fed's updated economic projections and Chair Kevin Warsh's press conference for signals on the future path of interest rates, particularly regarding potential additional tightening later in the year. Higher oil prices and persistent inflation pressures are also reinforcing expectations for a relatively hawkish policy stance.
Gold declined around 0.11% in the latest trading session, remaining below the $4,350 area as traders adopted a cautious stance ahead of the Fed decision. Rising US Treasury yields and expectations of tighter monetary policy continue to weigh on the non-yielding precious metal, while geopolitical tensions provide some underlying safe-haven support. The key focus remains on the Fed's rate decision, dot plot and guidance, which could determine the Dollar's next move and provide fresh direction for Gold.
WTI Crude Oil gained around 3.13% in the latest session, with prices remaining elevated near the $100–$105 area as Middle East supply-disruption concerns intensified. Saudi Arabia reportedly cancelled September crude deliveries to European customers after drone attacks forced the closure of its East-West pipeline, while broader tensions involving Iran and the Strait of Hormuz continue to support the oil risk premium.
Asian stock markets traded generally higher in the latest session as investors awaited the Federal Reserve's decision, with regional equities recovering modestly after recent losses. Semiconductor stocks were mixed: SK Hynix gained 4.21% and Samsung Electronics advanced 2.42%, while Kioxia declined 3.02% and TSMC slipped 0.21%. Broader market sentiment remained cautious as investors assessed elevated bond yields, oil prices and the outlook for global monetary policy.
Asian technology and consumer shares were mixed, with Alibaba rising 0.07%, while Meituan fell 0.48%, JD.com declined 0.62% and Tencent lost 0.94%. Investors continue to monitor China's uneven economic recovery, with stronger industrial activity contrasting with weak domestic consumption and property investment. Meanwhile, debate surrounding the economics and monetization of AI investment remains an important factor for technology valuations.
US equity markets ended lower in the latest session as rising Treasury yields and elevated oil prices weighed on risk sentiment. The US 10-year Treasury yield briefly moved above 5%, reaching its highest level since 2007, while investors positioned ahead of the Federal Reserve decision. US equity futures remain relatively cautious as markets await the Fed's policy statement and economic projections.
Bitcoin declined around 3.33% following the US Senate's failure to advance the CLARITY Act. The Senate voted 49–50 on the procedural motion, falling well short of the 60 votes required to move the legislation forward. The setback triggered broader weakness across the cryptocurrency market, with Bitcoin falling below $76,000 and major altcoins also coming under pressure. The focus now shifts toward monetary policy and the Federal Reserve decision, while the future of the CLARITY Act remains uncertain following the failed vote.
In the UK, August CPI inflation accelerated to 3.1% year-on-year from 2.9% in July, matching market expectations and remaining above the Bank of England's 2% target. Core inflation remained unchanged at 2.6%, while services inflation held at 3.4%. The data comes ahead of Thursday's Bank of England decision, with markets currently expecting rates to remain unchanged.
Looking ahead, the main market event is today's Federal Reserve interest-rate decision, scheduled for 6:00 PM GMT (9:00 PM Cyprus time), followed by Chair Kevin Warsh's press conference. Markets will focus not only on the rate decision but also on the updated projections and guidance for future policy. The Bank of England follows on Thursday, while the Bank of Japan concludes the week's major central-bank decisions on Friday.
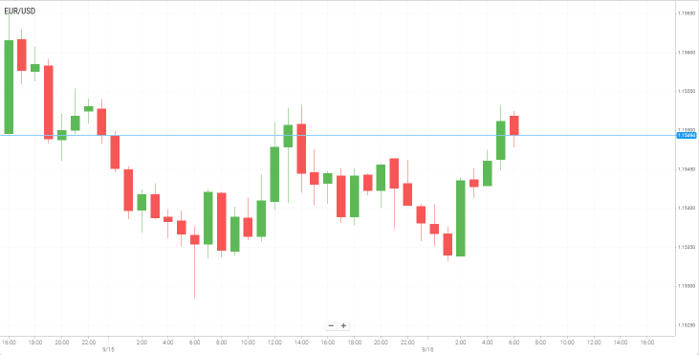
The EUR/USD pair remains under pressure for a fifth consecutive session, trading around the 1.1535–1.1530 region during Wednesday’s Asian session. The pair continues to hover near the one-month low reached on Monday as traders await the Federal Reserve’s highly anticipated policy decision for fresh direction.
The US Federal Reserve is set to conclude its September policy meeting today, with markets widely expecting a 25-basis-point rate hike. Attention will also focus on the Fed’s updated economic projections and Chair Kevin Warsh’s comments during the post-meeting press conference. These signals could provide further clues about the central bank’s interest-rate path in the coming months and influence the US Dollar’s near-term performance, as well as the EUR/USD pair.
Ahead of the decision, renewed inflation concerns linked to rising energy prices are strengthening expectations for continued monetary tightening. At the same time, increased government and corporate borrowing pushed the yield on the benchmark 10-year US Treasury note to its highest level since April 2007. Higher Treasury yields have provided additional support to the US Dollar and added pressure on EUR/USD.
However, the European Central Bank’s relatively hawkish policy outlook could provide some support for the Euro and help limit further losses in EUR/USD.
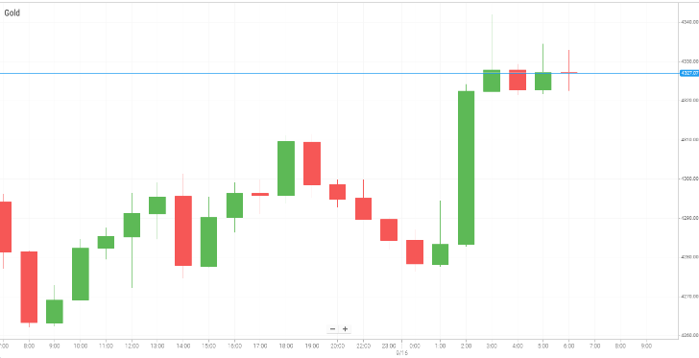
Gold remains on the defensive despite recovering from a modest decline earlier in the Asian session on Wednesday. The precious metal trades with slight gains but struggles to move above the $4,350 level as traders remain cautious ahead of the Federal Reserve’s highly anticipated interest-rate decision. However, uncertainty ahead of the key central bank event is keeping traders from taking aggressive directional positions.
The US Federal Reserve is scheduled to announce its policy decision later today and is widely expected to raise interest rates by 25 basis points (bps) following its September 15–16 meeting. Market attention will focus on the Fed’s updated economic projections, including the closely watched dot plot, as well as comments from Fed Chair Kevin Warsh during the post-meeting press conference. Any signals regarding the future path of interest rates could have a significant impact on the US Dollar and provide fresh direction for the non-yielding Gold price.
Geopolitical developments are also keeping markets on edge. Saudi Arabia issued security alerts covering several areas, including the holy city of Mecca and Jeddah, following a week of attacks by Iran-aligned Houthi forces in Yemen. The Saudi-led coalition has pledged to respond firmly to missile and drone attacks by the Houthi group, raising concerns over a further escalation of regional tensions.
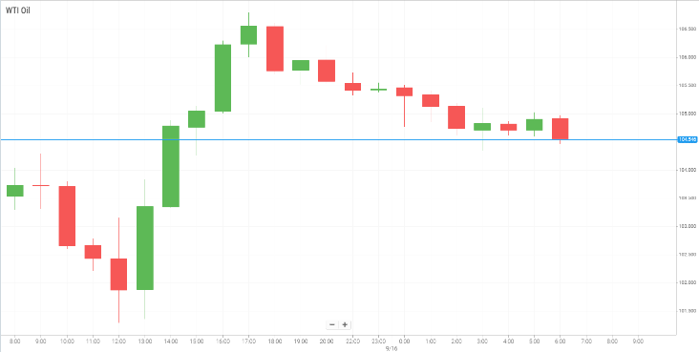
Oil prices moved lower on Wednesday after data showed an unexpected increase in US crude inventories, outweighing ongoing supply disruptions in the Middle East. Prices also came under pressure from some profit-taking following a sharp rally in recent weeks, driven by escalating hostilities between the Houthis and Saudi Arabia and the continued standoff in the Strait of Hormuz.
Market participants were also cautious about taking large positions ahead of the Federal Reserve’s closely watched policy decision later on Wednesday. The central bank is widely expected to raise interest rates, with investors focusing on its guidance regarding the future path of monetary policy and its potential impact on economic growth and fuel demand.
Data released by the American Petroleum Institute (API) showed that US crude inventories increased by 7.14 million barrels in the week ending September 11. The figure sharply contrasted with market expectations for a decline of around 1.8 million barrels.
The API report typically provides an indication of what to expect from the US Energy Information Administration’s official inventory figures, which are due later on Wednesday. The unexpected build suggests that stockpiles in the world's largest oil-consuming nation remain relatively well supplied despite ongoing disruptions to global crude flows.
Ongoing disruptions to crude supplies in the Middle East continued to provide a floor for oil prices. Reports indicated that Saudi Arabia halted loadings at its Yanbu port after the world's largest crude exporter shut its East-West pipeline following a series of attacks by Iran-aligned Houthi forces in recent weeks.
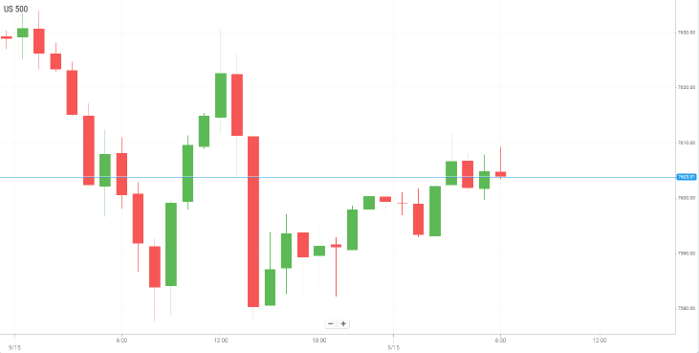
US stocks finished lower on Tuesday as a sharp rise in Treasury yields and surging oil prices weighed on market sentiment ahead of the Federal Reserve’s closely watched interest-rate decision. Investors largely remained on the sidelines as they awaited Wednesday’s policy announcement, with markets widely expecting the central bank to raise interest rates.
The pressure on equities was particularly evident in the bond market, where longer-dated Treasury yields climbed to multi-year highs. The benchmark 10-year Treasury yield rose 4.7 basis points to 5.008%, marking its highest level since April 2007. The 30-year Treasury yield also reached its highest level in more than two decades.
According to the CME FedWatch Tool, markets were pricing in a 94% probability of a 25-basis-point rate increase at Wednesday’s Federal Open Market Committee meeting, up significantly from 59% a week earlier. Investors will therefore be watching the Fed’s policy statement, economic projections and Chair Kevin Warsh’s comments closely for indications about the future direction of interest rates.
Meanwhile, technology stocks remained under scrutiny amid growing debate over the safety and regulation of artificial intelligence. The S&P 500 technology sector declined on Monday following concerns raised by figures within the AI industry, while semiconductor stocks suffered a sharper selloff.
The materials contained on this document should not in any way be construed, either explicitly or implicitly, directly or indirectly, as investment advice, recommendation or suggestion of an investment strategy with respect to a financial instrument, in any manner whatsoever. Any indication of past performance or simulated past performance included in this document is not a reliable indicator of future results. For the full disclaimer click here.
Join iFOREX to get an education package and start taking advantage of market opportunities.
 A beginner's e-book
 $5,000 practice demo account
 A 12-part video course
 Trusted partner

 Featured partner
 By


