
Listed on 
 Years active
 English (Arabic)
 Chinese Simplified - 中文 (简体)
 Chinese Traditional - 中文 (繁體)
 English
 Japanese - 日本語
 Korean - 한국어 (대한민국)
 Portuguese - Português
 Russian - Русский
 Spanish - Español
 Thai - ไทย

 English (India)

Don't have an account?
Register via AppHave an account?
Login 30/09/2026 - 07:11 UTC
The US Dollar Index (USDX) gathered further momentum, trading near 101.40 in Wednesday's early European session after rising 0.21% in the prior day. Greenback demand remains well-supported as markets price in nearly a 47.1% probability of an October rate hike and over 92% odds for December following hawkish remarks from Fed officials Austan Goolsbee and Michael Barr. Although benchmark Treasury yields retreated slightly, with the 30-year yield easing from multi-decade highs of 5.62% to around 5.55%, the USD remains poised for its largest monthly gain in 14 months.
Gold edged lower during Asian trading, surrendering part of the previous day's gains, which had seen XAU/USD bounce 1.40% off multi-month lows near $4,100 per ounce. Persistent bets on additional Fed monetary tightening and firm greenback momentum remain primary headwinds for non-yielding bullion, though safe-haven interest tied to Middle East tensions continues to cushion steeper downside.
WTI Crude Oil bounced to around $88.30 per barrel after tumbling 4.43% on Tuesday, while Brent crude held near $103. Prices found support after US President Donald Trump rejected reports of potential sanctions relief or frozen fund releases for Iran, maintaining a high geopolitical risk premium. However, upside remains capped as Middle East exports recovered to 98% of pre-conflict levels, bolstered by Saudi Arabia resuming pipeline flows and API reporting a 1.019 million barrel increase in US crude stockpiles.
Asian stock markets traded mostly higher on Wednesday, as a temporary retreat in global bond yields provided relief to risk assets. Japan's Nikkei led regional gains, driven by tech strength and a massive surge in SoftBank Group, which rallied 8.19%. Elsewhere in the region, tech heavyweights posted mixed sessions, with SK Hynix gaining 0.91% while Samsung Electronics fell 0.91%.
US equity indexes closed modestly lower overnight, though AI enthusiasm boosted by news of Anthropic preparing for a massive IPO debut, helped major cap-weighted benchmarks recover from intra-day lows. Megacap tech names showed divergence, with Nvidia dipping 0.74% while Meta advanced 3.23%. Meanwhile, broader risk sentiment was impacted by US consumer confidence dropping to an over 12-year low.
Looking ahead, market participants are focused on a heavy schedule of macroeconomic data, including the US Core PCE Price Index m/m, Final GDP q/q, ADP Employment Change, JOLTS Job Openings, ISM Manufacturing PMI, and EIA Crude Oil Stockpiles. Investors are also watching Friday's Non-Farm Employment Change and Unemployment Rate, upcoming Fed speeches, diplomatic developments around the Strait of Hormuz, and corporate earnings releases from Carnival Corp, Micron, Accenture, and Nike.
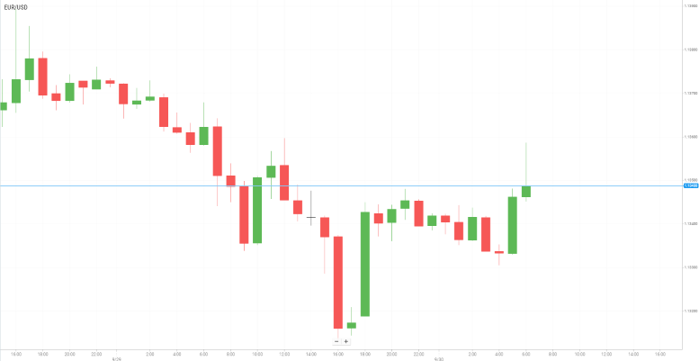
The EUR/USD pair remains under selling pressure for the third consecutive day, trading around the 1.1330 region during the Asian session on Wednesday. The pair remains close to its lowest level since May 2025, reached the previous day, as the broader fundamental backdrop continues to favor the US Dollar. The combination of a stronger USD, dovish signals from the European Central Bank, and ongoing geopolitical uncertainty is weighing on the Euro and keeping the downside bias intact.
ECB President Christine Lagarde's dovish-leaning comments on Tuesday reduced market expectations for another interest-rate hike in October, putting additional pressure on the shared currency. Meanwhile, the USD continues to trade near a two-month high, providing another source of downward pressure on EUR/USD.
The initial reaction to comments from New York Federal Reserve President John Williams was short-lived. Williams said on Tuesday that the US central bank does not need to rush its next policy move, but markets continue to price in a more than 90% probability of a rate hike by the end of the year.
Hopes for a diplomatic resolution to the US-Iran conflict have also weakened after US President Donald Trump rejected a seven-day ceasefire proposal from Iran. Efforts by Qatar to broker a breakthrough between Washington and Tehran have made limited progress this week. Meanwhile, US officials reportedly believe Trump could order a return to major combat operations against Iran following the November midterm elections.
Attention will then turn to the closely watched US monthly employment report, commonly known as the Nonfarm Payrolls (NFP) report, which is scheduled for Friday. Speeches from influential Federal Open Market Committee (FOMC) members will also be monitored for further clues regarding the Federal Reserve's monetary-policy outlook.
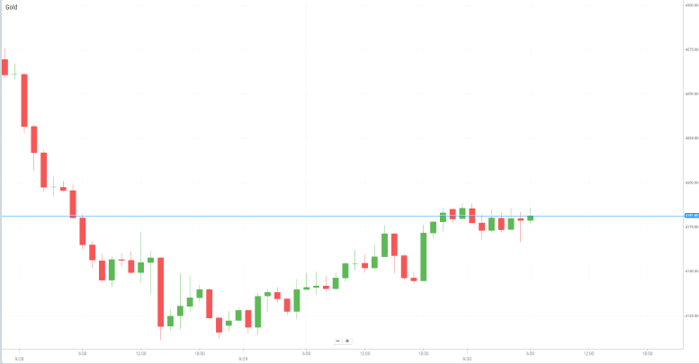
Gold edged lower during the Asian session on Wednesday, giving back part of the previous day's modest recovery from the $4,100 area, which marked the metal's lowest level since August 5 earlier this week. However, the downside remains relatively limited as traders await a series of important US economic releases before committing to fresh directional positions in Gold.
The main focus is on the US Personal Consumption Expenditures (PCE) Price Index, the Federal Reserve's preferred measure of inflation, which is due later today alongside the final second-quarter GDP figures. Markets will also assess the US ISM Manufacturing PMI on Thursday before turning their attention to the closely watched Nonfarm Payrolls (NFP) report on Friday. In addition, comments from influential Federal Open Market Committee (FOMC) members could provide further clues about the Fed's monetary-policy outlook. The direction of the US Dollar (USD), in turn, is likely to remain a key driver for Gold prices.
At the same time, continued uncertainty surrounding the US-Iran standoff is supporting demand for the safe-haven USD. Hopes for a diplomatic resolution weakened after US President Donald Trump rejected a seven-day ceasefire proposal from Iran. Efforts by Qatar to facilitate negotiations between the two sides have also made limited progress this week.
Further reports that US officials believe Trump could order a return to major combat operations after the midterm elections have added to concerns about a renewed escalation in the Middle East. The ongoing geopolitical risk could therefore continue to support the USD and limit demand for Gold in the near term.
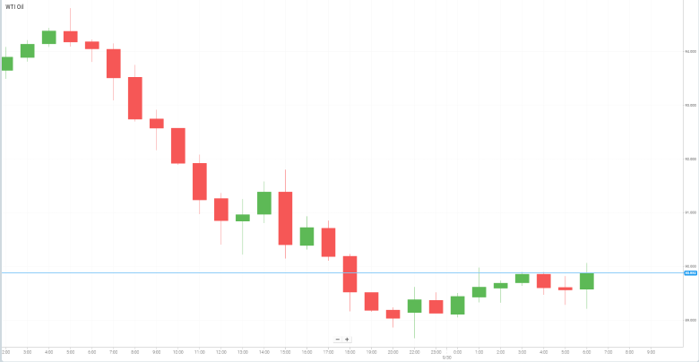
Oil prices were largely unchanged on Wednesday after falling sharply in the previous session, as signs of recovering crude exports from the Middle East helped offset concerns over continued disruptions to shipments through the Strait of Hormuz.
The latest pressure on oil prices followed Saudi Arabia's resumption of crude loadings at its Red Sea port of Yanbu after flows through the East-West Pipeline were restored. The pipeline provides an alternative export route that bypasses the Strait of Hormuz, reducing some of the immediate supply risks associated with disruptions in the strategic waterway.
Saudi Aramco has informed customers of its October loading schedule, while shipping data showed that nearly 10 million barrels of crude were being loaded at Yanbu and the nearby Al Muajjiz port, according to a Reuters report. Saudi Arabia has also restored flows through the East-West Pipeline to at least 3.5 million barrels per day, roughly half of its total capacity, Bloomberg reported, citing people familiar with the matter.
Qatar is currently mediating between Washington and Tehran, with discussions reportedly focused on a potential agreement that could include reopening the Strait of Hormuz and reducing some US pressure on Iran. However, the diplomatic process remains uncertain. US President Donald Trump has rejected reports that Washington offered Tehran sanctions relief, while Iran has continued to push for conditions linked to reopening the strategically important waterway.
Meanwhile, concerns over the impact of elevated energy prices on the US economy and consumers are adding another layer of uncertainty to the oil market. A Financial Times report indicated that Trump is considering several measures, including a possible diesel export ban, in an effort to contain surging domestic fuel prices. The move comes as the worsening energy situation increases political pressure on the administration.
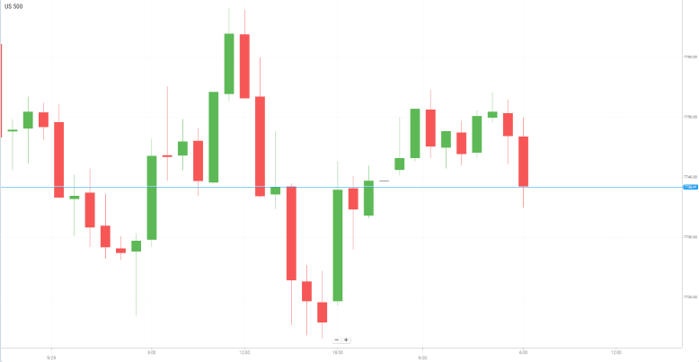
US stocks ended slightly lower on Tuesday as a sharp selloff in the Treasury market pushed longer-term bond yields to fresh multi-decade highs before a late-session recovery helped ease some of the pressure. The bond-market selloff remained the main focus for investors, with the 10-year and 30-year Treasury yields reaching their highest levels in more than two decades.
Investors are now turning their attention to upcoming US economic data for further clues about the Federal Reserve's policy path. The market is particularly focused on Wednesday's release of the Fed's preferred inflation gauge and Friday's Nonfarm Payrolls report. Consumer confidence also weakened significantly in September. The Conference Board's consumer confidence index fell to 81.9, well below the expected 89.2 and marking its lowest level since May 2014. The softer economic data helped ease some pressure on Treasury markets, although investors continue to monitor signs of persistent inflation and labor-market resilience.
Despite the broader pressure from rising yields, technology and artificial intelligence-related stocks helped limit the decline in major indexes. The AI trade recovered after a volatile start to the week, supported in part by reports that Anthropic is preparing for a potential initial public offering that could value the company at more than $2 trillion. The AI sector remains a major source of support for the broader US equity market, even as other parts of the market show signs of weakness.
Anthropic's reported IPO plans have added further attention to the sector. According to Reuters, the company expects its cloud, computing and infrastructure commitments to reach approximately $518 billion over the coming year. The company generated nearly $4.6 billion in revenue in 2025, although it reported a substantial net loss that included a large accounting charge related to financing instruments that could convert into shares.
Among individual stocks, Carnival was one of the strongest performers in the US 500, rising more than 13% after the cruise operator reported better-than-expected adjusted quarterly earnings.
The materials contained on this document should not in any way be construed, either explicitly or implicitly, directly or indirectly, as investment advice, recommendation or suggestion of an investment strategy with respect to a financial instrument, in any manner whatsoever. Any indication of past performance or simulated past performance included in this document is not a reliable indicator of future results. For the full disclaimer click here.
Join iFOREX to get an education package and start taking advantage of market opportunities.
 A beginner's e-book
 $5,000 practice demo account
 A 12-part video course
 Trusted partner

 Featured partner
 By


