
Listed on 
 Years active
 English (Arabic)
 Chinese Simplified - 中文 (简体)
 Chinese Traditional - 中文 (繁體)
 English
 Japanese - 日本語
 Korean - 한국어 (대한민국)
 Portuguese - Português
 Russian - Русский
 Spanish - Español
 Thai - ไทย

 English (India)

Don't have an account?
Register via AppHave an account?
Login 25/09/2026 - 06:31 UTC
The US Dollar Index (USDX) maintained its bullish momentum, rising 0.12% to trade near 101.80 during Asian hours on Friday. The Greenback remained well supported by soaring US Treasury yields, which saw the 10-year yield approach 19-year highs near 5.23%. Sustained dollar strength was propelled by persistent hawkish rhetoric from Federal Reserve officials, led by New York Fed President Williams, alongside sticky inflation concerns and higher energy costs. Market expectations via the CME FedWatch tool now price in nearly a 50% to 70% chance of further Fed rate hikes before year-end, keeping borrowing costs elevated and underpinning dollar demand.
Gold traded lower on Friday, slipping 0.55% as rising global bond yields and firm rate-hike expectations continued to dampen demand for non-yielding bullion. While lingering geopolitical risks in the Middle East provided a modest floor, persistent greenback strength and elevated Treasury yields restricted any significant safe-haven rebound, keeping precious metals under sustained pressure.
WTI Crude Oil bounced back, gaining 2.00% to trade around $92.60 per barrel following a volatile session. Energy prices initially slid on headlines that Qatari-mediated talks between the US and Iran at the UN General Assembly were exploring a phased deal to reopen the strategic Strait of Hormuz. However, crude quickly regained upside traction after Saudi Arabia intercepted six Houthi ballistic missiles targeting key regional cities. Continued supply anxiety, coupled with the US energy surplus providing a relative buffer for domestic manufacturers, reignited inflationary fears across broader markets.
Asian stock markets traded mostly lower on Friday as a global bond sell-off pushed yields across regional sovereign debt to multi-year highs. Mainland Chinese, South Korean, and Taiwanese markets were closed for holidays, resulting in thin liquidity. Japan's Nikkei bucked the trend by gaining some momentum on exporter strength, while Hong Kong's Hang Seng slid nearly 2%. Major regional tech names posted mixed results: SK Hynix fell 0.99%, while Samsung Electronics advanced 2.53%.
US equities ended little changed after paring sharp early losses triggered by surging yields and oil price spikes. Investor sentiment was partially supported by news that US President Donald Trump and Chinese President Xi Jinping agreed to a two-month trade truce extension to negotiate tariffs, rare-earth supplies, and technology restrictions. Individual market movers reflected shifting tech dynamics: Meta surged 4.51% as its new autonomous AI agent, Muse, dominated app downloads, while Nvidia slipped 0.39% and Oracle dropped 3.43% following project disruption reports at its New Mexico data center.
Looking ahead, market participants face a packed economic calendar that will keep global interest rate expectations and volatility at the forefront. Alongside monitoring full diplomatic readouts from the Trump-Xi summit and geopolitical updates regarding the Strait of Hormuz, key catalysts kick off on Tuesday, September 29, with the Reserve Bank of Australia’s Cash Rate decision, followed closely by Australia's monthly CPI figures on Wednesday. Essential inflation data—including the US Core PCE Price Index on Wednesday and Eurozone Core CPI estimates on Friday—will further shape policy outlooks for the Fed and ECB. Investor focus will culminate on Friday, October 2, with the marquee US Non-Farm Payrolls report, average hourly earnings, and the unemployment rate, which together will heavily dictate the next directional move for bond yields, corporate earnings sentiment, and the US dollar.
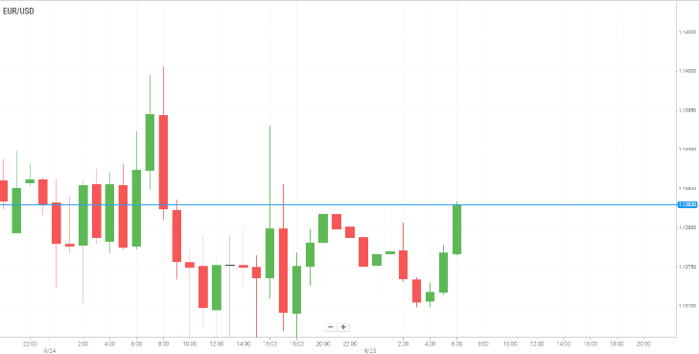
The EUR/USD pair traded with modest losses near 1.1375 during early Asian trading on Friday, as the US Dollar strengthened against the Euro amid increasingly hawkish signals from Federal Reserve officials and limited progress in US-Iran negotiations. Traders are now turning their attention to further comments from Fed officials later on Friday.
US Treasury yields continued to climb, with the 30-year Treasury yield reaching 5.501%, its highest level since June 2004, while the 10-year Treasury yield rose to 5.223%, a level not seen since June 2007. Rising oil prices, resilient US economic activity and hawkish comments from Fed policymakers have prompted markets to increase their expectations for another interest-rate hike.
Philadelphia Fed President Anna Paulson said on Thursday that additional monetary tightening could be necessary if the economy continues to develop as expected. She also noted that inflation remains well above the Federal Reserve’s 2% target.
Meanwhile, negotiations between the United States and Iran have shown limited signs of progress. The uncertainty surrounding the US-Iran negotiations, together with ongoing conflicts in the Middle East, could continue to support demand for safe-haven assets such as the US Dollar, creating additional pressure on EUR/USD.
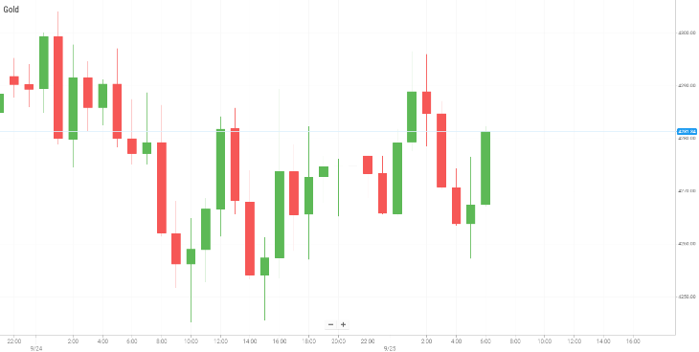
Gold remained in a consolidation phase below $4,300 during early Asian trading on Friday, holding near the weekly low reached in the previous session. The precious metal continues to face a challenging fundamental backdrop as expectations for a hawkish Federal Reserve, elevated US Treasury yields and persistent geopolitical uncertainty support the US Dollar.
The broader strength of the Greenback, combined with higher US bond yields, continues to weigh on the non-yielding precious metal and keeps prices below the $4,300 level. Gold also remains on track to record weekly losses, leaving the pair vulnerable to further downside pressure.
Federal Reserve officials have continued to adopt a more hawkish tone following the September rate hike, signaling that additional monetary tightening could remain on the table.
With the Fed maintaining a hawkish stance, US bond yields remaining elevated and the Dollar holding near recent highs, gold continues to face downward pressure. Unless the US Dollar weakens significantly or expectations for further Fed tightening ease, the precious metal could remain vulnerable as traders assess the outlook for interest rates and inflation.
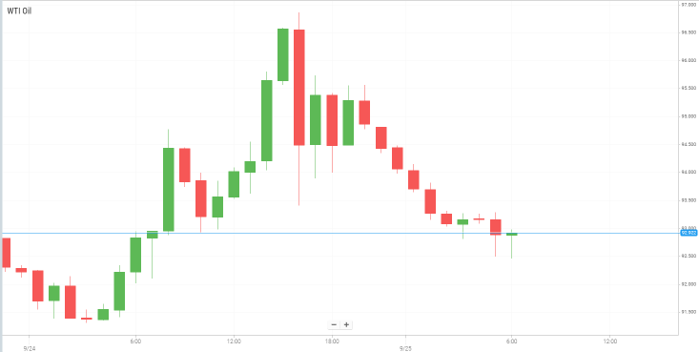
Oil prices edged lower on Friday as markets weighed the possibility of a truce between the United States and Iran against continued attacks on energy infrastructure in the Middle East. The decline came after a highly volatile week in which crude prices surged amid growing concerns over potential disruptions to global oil supplies.
Brent recorded its highest closing level since September 15, while Thursday’s advance marked WTI’s first daily gain after six consecutive sessions of losses.
Meanwhile, US and Iranian negotiators in New York are reportedly exploring a phased path toward ending the conflict. Sources close to the discussions said a potential agreement could involve Iran reopening the Strait of Hormuz in exchange for Washington lifting its economic blockade of Iran.
The Strait of Hormuz remains critical to global energy markets, and any disruption to the waterway could have significant consequences for oil and gas supplies. Since the war began in late February, around one-fifth of global oil and gas shipments have reportedly been curtailed, contributing to a sharp increase in energy prices and prompting liquefied natural gas buyers to seek alternative sources of supply.
Iranian President Masoud Pezeshkian said on Thursday that it was up to the United States to decide when the conflict should end. His comments came as negotiations continued, although uncertainty remains over whether the two sides can reach an agreement.
At the same time, continued attacks in the region are keeping supply concerns firmly in focus. Saudi Arabia said it had intercepted six ballistic missiles launched by Yemen’s Iran-backed Houthi movement, targeting areas including the southern province of Taif and the Yanbu region along the Red Sea.
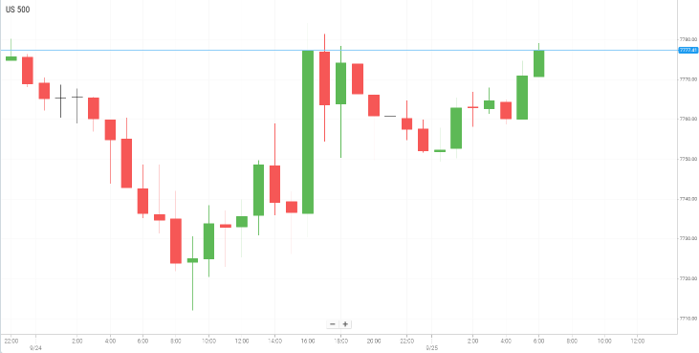
US stocks finished largely unchanged on Thursday after a volatile session as investors weighed the combined impact of rising oil prices, higher Treasury yields and increasingly hawkish signals from the Federal Reserve. Equities initially came under pressure but recovered some ground after reports emerged that the United States and Iran were discussing a potential phased agreement to end their conflict.
Investors have been closely watching diplomatic efforts between Washington and Tehran, particularly during the United Nations General Assembly in New York. US and Iranian officials have held indirect discussions, although US Secretary of State Marco Rubio said the talks should not be characterized as a major breakthrough.
Geopolitical developments involving China were also in focus as Chinese President Xi Jinping visited the White House for his first US state visit since 2015. President Donald Trump said the two leaders would discuss issues including security, technology and artificial intelligence. Trump also said Washington and Beijing had been working toward a more balanced trading relationship, while Xi emphasized the importance of maintaining a stable course for US-China relations.
Trade and artificial intelligence are expected to feature prominently in discussions between the two leaders as Washington and Beijing continue competing in strategic technology sectors.
Among individual stocks, Meta Platforms gained 4.5% as investor enthusiasm surrounding its new consumer AI agent, Muse, continued to support the shares. The company’s AI platform has attracted attention for its ability to perform multi-step tasks such as booking travel, managing calendars and making online purchases.
The materials contained on this document should not in any way be construed, either explicitly or implicitly, directly or indirectly, as investment advice, recommendation or suggestion of an investment strategy with respect to a financial instrument, in any manner whatsoever. Any indication of past performance or simulated past performance included in this document is not a reliable indicator of future results. For the full disclaimer click here.
Join iFOREX to get an education package and start taking advantage of market opportunities.
 A beginner's e-book
 $5,000 practice demo account
 A 12-part video course
 Trusted partner

 Featured partner
 By


